Elevate your local knowledge
Sign up for the iNFOnews newsletter today!
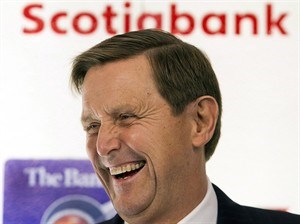
TORONTO – Scotiabank’s second-quarter net income rose to $1.6 billion — up about $140 million from a year ago — but its adjusted earnings fell short of analyst estimates.
The bank’s adjusted earnings came in at $1.24 per share, up from $1.16 a year in the second quarter of 2012 but two cents below a consensus estimate.
Scotiabank (TSX:BNS) says its profit attributable to common shareholders amounted to $1.23 per share of diluted earnings, up from $1.15 per share in the second quarter of 2012.
Canada’s most international bank said its Canadian banking sector produced less than one-third of its overall profit, or $547 million.
That was nearly matched by its international banking operations, which had $471 million of net income during the quarter.
Wealth management produced about $335 million of Scotiabank’s overall profit while global banking and markets added $361 million.
“We continue to have very strong results this quarter driven by very good revenue growth. Each business line made a solid contribution to these good results” said Rick Waugh, Scotiabank CEO, said in a statement.
“Our diversification and straightforward business model have allowed us to take advantage of opportunities to grow.”
Scotiabank said recent acquisitions contributed $61 million to the year-over-year growth in net income.
It said the remaining increase was from higher net interest income, growth in transaction-based fees and wealth management revenues and increased net gains on investment securities. The growth was partly offset by lower trading revenues, increased operating expenses and higher provisions for credit losses.
Scotiabank’s overall provision for credit losses — which banks take in anticipation that some loans won’t be repaid fully — increased to $343 million.
That was up from $264 million in the second quarter of 2012 and $434 million in the first quarter of 2013, ended Jan. 31.
Scotiabank said the year-over-year increase was due to higher provisions for credit losses across all business lines, with the largest increases in international retail banking and Canadian commercial banking.
News from © The Canadian Press, . All rights reserved.
This material may not be published, broadcast, rewritten or redistributed.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.