Elevate your local knowledge
Sign up for the iNFOnews newsletter today!
Court-ordered real estate sales in Kelowna increased fourfold in the last five years, and 2026 is on track to go even higher.
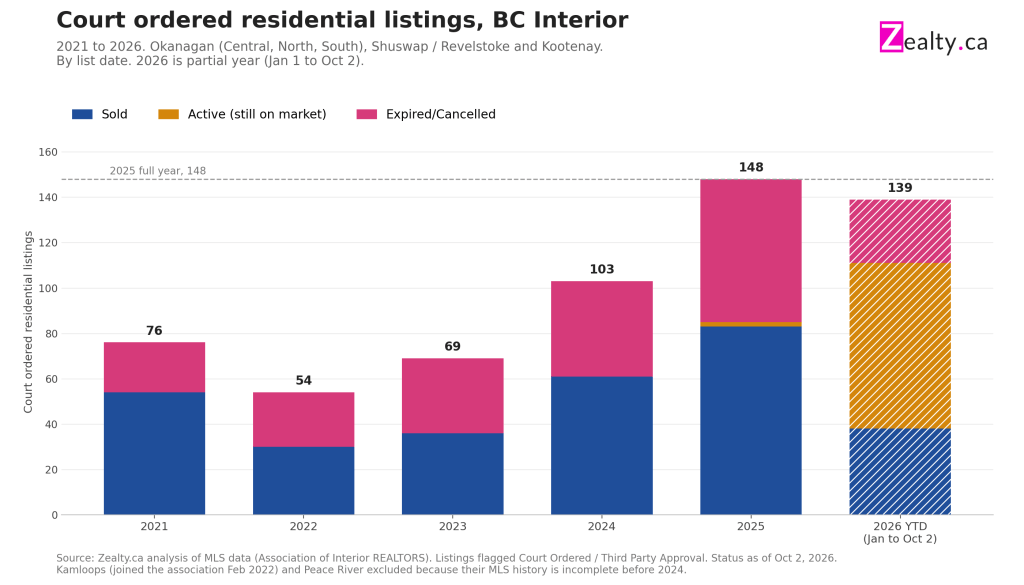
Data from property search platform Zealty.ca shows that court-ordered listings across the Okanagan went from 35 in 2021 to 111 last year. So far this year, up until the beginning of October, there has been 102, showing that it’s likely to surpass last year.
In the Southern Interior, Kelowna accounts for most of the court-ordered sales, with the number jumping to 61 in 2025, up from 15 in 2021. Up until the beginning of October, there have been 49 court-ordered sales this year.
With interest prime lending rates slashed to 2.45% at the onset of COVID and staying low for two years, anyone renewing their mortgage in the last couple of years has had to deal with the higher rates – currently sitting at 4.7% – and with those rates come steeper payments.
“Everyone is expecting a raise and most people are shocked that it’s not more,” Vernon mortgage broker Jeremy Schaffner told iNFOnews.ca. “I certainly haven’t seen anyone panic-stricken, obviously no one wants their payments to increase, but nobody seems to have been forced to sell or completely refinance.”
While the numbers are clear, Schaffner suggested that growth might be more isolated because he hasn’t seen much doom and gloom.
He recently did a renewal on a $620,000 mortgage taken out five years ago. That mortgage now sits at $515,00 and the monthly payment has increased from $2,900 to $3,300.
Court-ordered sales data doesn’t show whether those properties were someone’s home or not but Schaffner suspects speculators.
“Everybody was eager to buy in the upswing and rent out… then of course the Airbnb ban came in and quashed a lot of that,” he said. “All of a sudden when you can’t rent for $200 a night and it’s got to be $1,500 a month or $2,000 a month, it definitely changes things.”
Across the Southern Interior, the median price for a court-ordered sale is $626,500, with 16% of sales involving property over $1 million. Of the 44 Okanagan court-ordered sales that closed this year, 84% sold below their BC Assessment value.
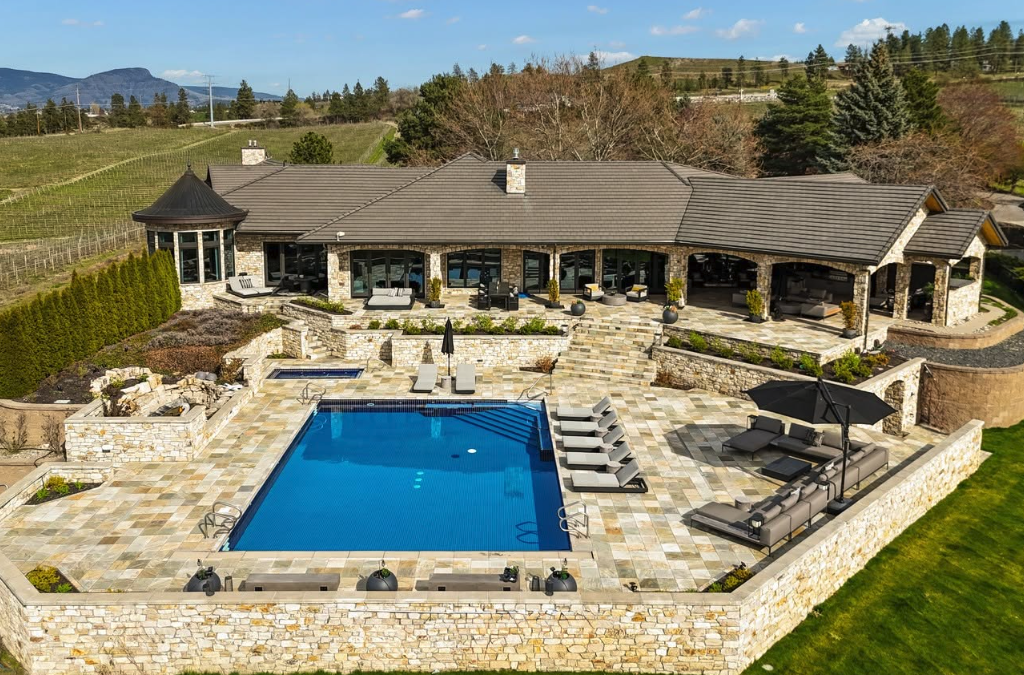
The priciest listing this year was a house on Casorso Road in Kelowna, which was listed for $7.9 million in a court-ordered sale and sold for $7.2 million.
Mortgage broker Brock Rodgers deals with clients in the Shuswap and North Okanagan and said he hasn’t seen any dire situations.
“I have seen lenders be more competitive with their renewal rates than they’ve ever been,” Brock said. “Simply because it’s a tough market for everyone, including lenders.”
He doubts working families are defaulting on debts just because of interest rates. Brock said for anyone whose mortgage is under $500,000 it might be a $100 to $300 increase.
“There’s lots of clients where… $200 hurts a lot, and there’s a lot of clients… (where) $400 doesn’t hurt at all,” he said.
Sometimes clients can re-amortize, taking their mortgage back to 25 years, but keeping the payments lower. While doing that isn’t ideal, it does take the stress off.
It appears that most people were expecting it to be worse than it is.
Kelowna mortgage broker Daryl French said the vast majority of people renewing their mortgages are actually pleasantly surprised.
“They’re coming in thinking their payments are going to go up $500 or $1,000,” he said.
Depending on their mortgage, the reality is often far lower.
“It’s been very busy on renewals the last two years and we’re not seeing any problems. Most clients that we’re dealing with are able to make the adjustment,” he said.
However, those with a closed variable mortgage, where the monthly payment stays the same regardless of the interest rate, will be hit the hardest.
“Those are the ones that I think hurt the most…they’ve gone backwards on their amortization and haven’t paid down their mortgage like a conventional mortgage,” French said. “Now instead of having a lower balance and a higher interest rate you’ve got a higher balance and a higher interest rate right, that hurts.”
Payments on this type of mortgage are likely to go up substantially.
French, like Schaffner, credits the stress test for keeping people out of trouble.
The stress test required all borrowers to qualify at the rate of 5.2% regardless of what the actual rate was. French said he wasn’t supportive of it originally.
“But you look at today… we’re now renewing mortgages in that… mid-4 % range and people qualified at 5.2%,” he said. “(The increase) shouldn’t in theory be a problem.”
French says the court-ordered sales stats don’t show the whole picture, pointing out that in 2021 people in financial trouble could sell their property in a week, so there was no need to go into foreclosure.
Zealty.ca president Hamidreza Etebarian said province-wide, 2026 has seen more than 1,000 court-ordered sales, the highest in 20 years.
“It shows that there is issues and there’s problems,” Etebarian said.
In the financial crisis in 2009, the issue was unemployment affecting working and middle-class people. Now the issue is interest rates, Etebarian said.
“It’s a mix of any… demographic,” Etebarian said. “Even wealthy people are actually struggling because they upgraded too much, they couldn’t afford it and now we’ve seen a mix of investors, individuals, families, rich people, middle-class people, and lower-class people basically struggling with their mortgages… all because… the rates have gone up.
“The numbers are… quite shocking,” he said.
News from © iNFOnews.ca, . All rights reserved.
This material may not be published, broadcast, rewritten or redistributed.
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Want to share your thoughts, add context, or connect with others in your community?
You must be logged in to post a comment.